Home > Resources > Manuals >
This is some text inside of a div block.

Chapter 5 of

ESL Returns in Portugal
Value Added Tax (VAT)
Local Language:
Imposto sobre o Valor Acrescentado (IVA)
portugal view
VAT Rates
Standard rate
23%
Reduced rate
13% and 6%

Due date and frequency of ESL returns in Portugal

The due date for submitting monthly or quarterly ESL returns is always the 20th day of the following month.

The frequency of filing depends on the reporting periods for VAT as well as on the turnover of intra-Community transactions.

  • Period
    Frequency rules
  • Monthly
    When the taxpayer submits the periodic VAT return on a monthly basis.
    Or, when the amount of intra-Community transactions exceeds EUR 50,000. This change is final.
  • Quarterly
    The amount of intra-Community transactions does not exceed EUR 50,000.

Find here the taxpayer’s calendar published by the Portuguese tax authorities, where the ESL returns are included.

‍

Nil and corrective ESL returns in Portugal

If there are no intra-Community transactions to be reported in a given period, a nil ESL is NOT due.

Corrective ESL returns in Portugal are prepared and submitted electronically by ticking the option 2 in the form: Declaração de substituição. Then you will need to choose the reason for submitting the corrective ESL return by ticking one of the following 4 boxes and corresponding sections within each one.
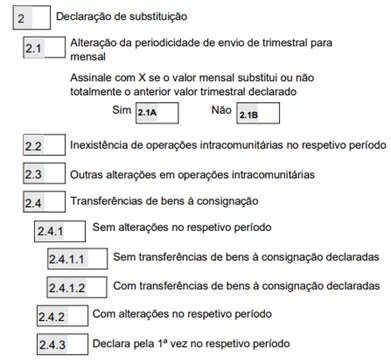
  • Field 2.1, when you have changed the frequency of filing from quarterly to monthly (this field must be completed when the threshold of €50,000 is exceeded). This field concerns exclusively intra-community transmissions of goods and similar operations.If you tick this field, you must indicate whether the amount to be declared in that month completely replaces, or not, the amount already declared for the quarter to which that month belongs (2.1A or 2.1B).
  • Field 2.2, due to the lack of intra-community operations in the respective period (this field must be completed when, having completed Table 04, it is verified that, in that period, there are no operations to be declared due to: cancellation of the operation, regularization or any other occurrence).
  • Field 2.3, for any other changes verified in relation to Tables 04 and 05 of the previously sent declaration (corrections to the amounts declared in relation to intra-community operations, as a result of regularizations, omissions or rectification of invoices, change of the NIF of the acquirer, of the Member State of destination or prefix, etc.).
  • Field 2.4: Field exclusively intended to indicate the occurrence during the period of intra-community transfers of consignment goods to be detailed in Table 06. Mandatory field to be completed whenever submitting a summary replacement declaration, and if there are no transfers in the period, the fields 2.4.1 and 2.4.1.1.

‍

Penalties for late ESL returns in Portugal

The same penalties as for VAT and Intrastat returns apply. The late submission of ESL returns is punished with a penalty ranging from EUR 150 to EUR 3,750.

The above penalties are regulated in Article 116 RGIT (REGIME GERAL DAS INFRAÇÕES TRIBUTÁRIAS).

‍

Latest news

london view

UK E-Invoicing Roadmap: One 2029 Start Date, Requirements by April 2028

The UK e-invoicing roadmap confirms 1 April 2029 start for all VAT-registered businesses, with final rules by April 2028. See the key dates.

norway city view

E-Invoicing in Norway: Complete Guide

Norway requires B2B e-invoicing from 1 January 2027. See the approved formats, exemptions, the 2030 timeline and how Peppol and EHF fit in.

poland city view

VAT Changes in Poland from 2027: VAT Warehouses and Wider Joint Liability

From 2027, Poland introduces a VAT warehouse procedure, extends joint liability to certain services and tightens fiscal representation rules.

switzerland view

Switzerland Plans to Increase VAT Rates From 2028

Swiss voters decide on 29 November 2026 on raising the standard VAT rate to 8.5% from 2028 to fund the 13th AHV pension. See what changes.

switzerland view

Switzerland Extends Special VAT Rate for Accommodation Services

Swiss accommodation services keep the 3.8% special VAT rate until the end of 2031, subject to an optional referendum. Find out what changes.

E-invoicing in Spain: Complete Guide

Mandatory B2B e-invoicing in Spain is confirmed. See who’s in scope, go-live dates from 2027, SPFE requirements and how to ensure compliance.

Why It May Be Time to Revisit Your E-Invoicing Strategy

Most e-invoicing strategies were never chosen, just built deadline by deadline. Compare four approaches to e-invoicing mandates and choose deliberately.

poland city view

Poland Plans 23% VAT Rate for Non-Alcoholic Beer, Wine and Selected Beverages

Poland plans to increase the VAT rate on non-alcoholic beverages and energy drinks with 20% fruit or vegetable juice content.

paris view

E-Invoicing in France: Complete guide

Mandatory B2B e-invoicing and e-reporting in France: rules, implementation calendar, simplification measures and certified Plateformes Agréées.

bulgaria view

E-Invoicing in Bulgaria: Complete Guide

Bulgaria proposes mandatory B2B e-invoicing from 2028: scope, NRA validation system, pre-filled VAT returns, penalties and implementation calendar.





